Saving for College When Your Kids Are Still Young
A Q&A on Starting Early
 September 02, 2026
- Communications & Marketing
Chris Brune, Ph.D., CFP® is a professor of finance in the Hickingbotham School of Business, where he also serves as chair of the Department of Accounting and Finance and sponsors the Ary Student Investment Fund, managing millions of the university’s endowment. We recently sat down with Dr. Brune to hear his thoughts on questions that parents are asking — and what questions they should be asking about financial planning for college.
While you’re here, learn more about Ouachita scholarships or look at a free budget worksheet provided by Dr. Brune.
Part 1 | Part 2 | Part 3 | Part 4
If your children are still young, you have the one advantage money can’t buy back: time. If your children are older, jump to part 4!
Dr. Brune explains why the habit matters more than the dollar amount. This is part 3 in a series on planning and paying for college.
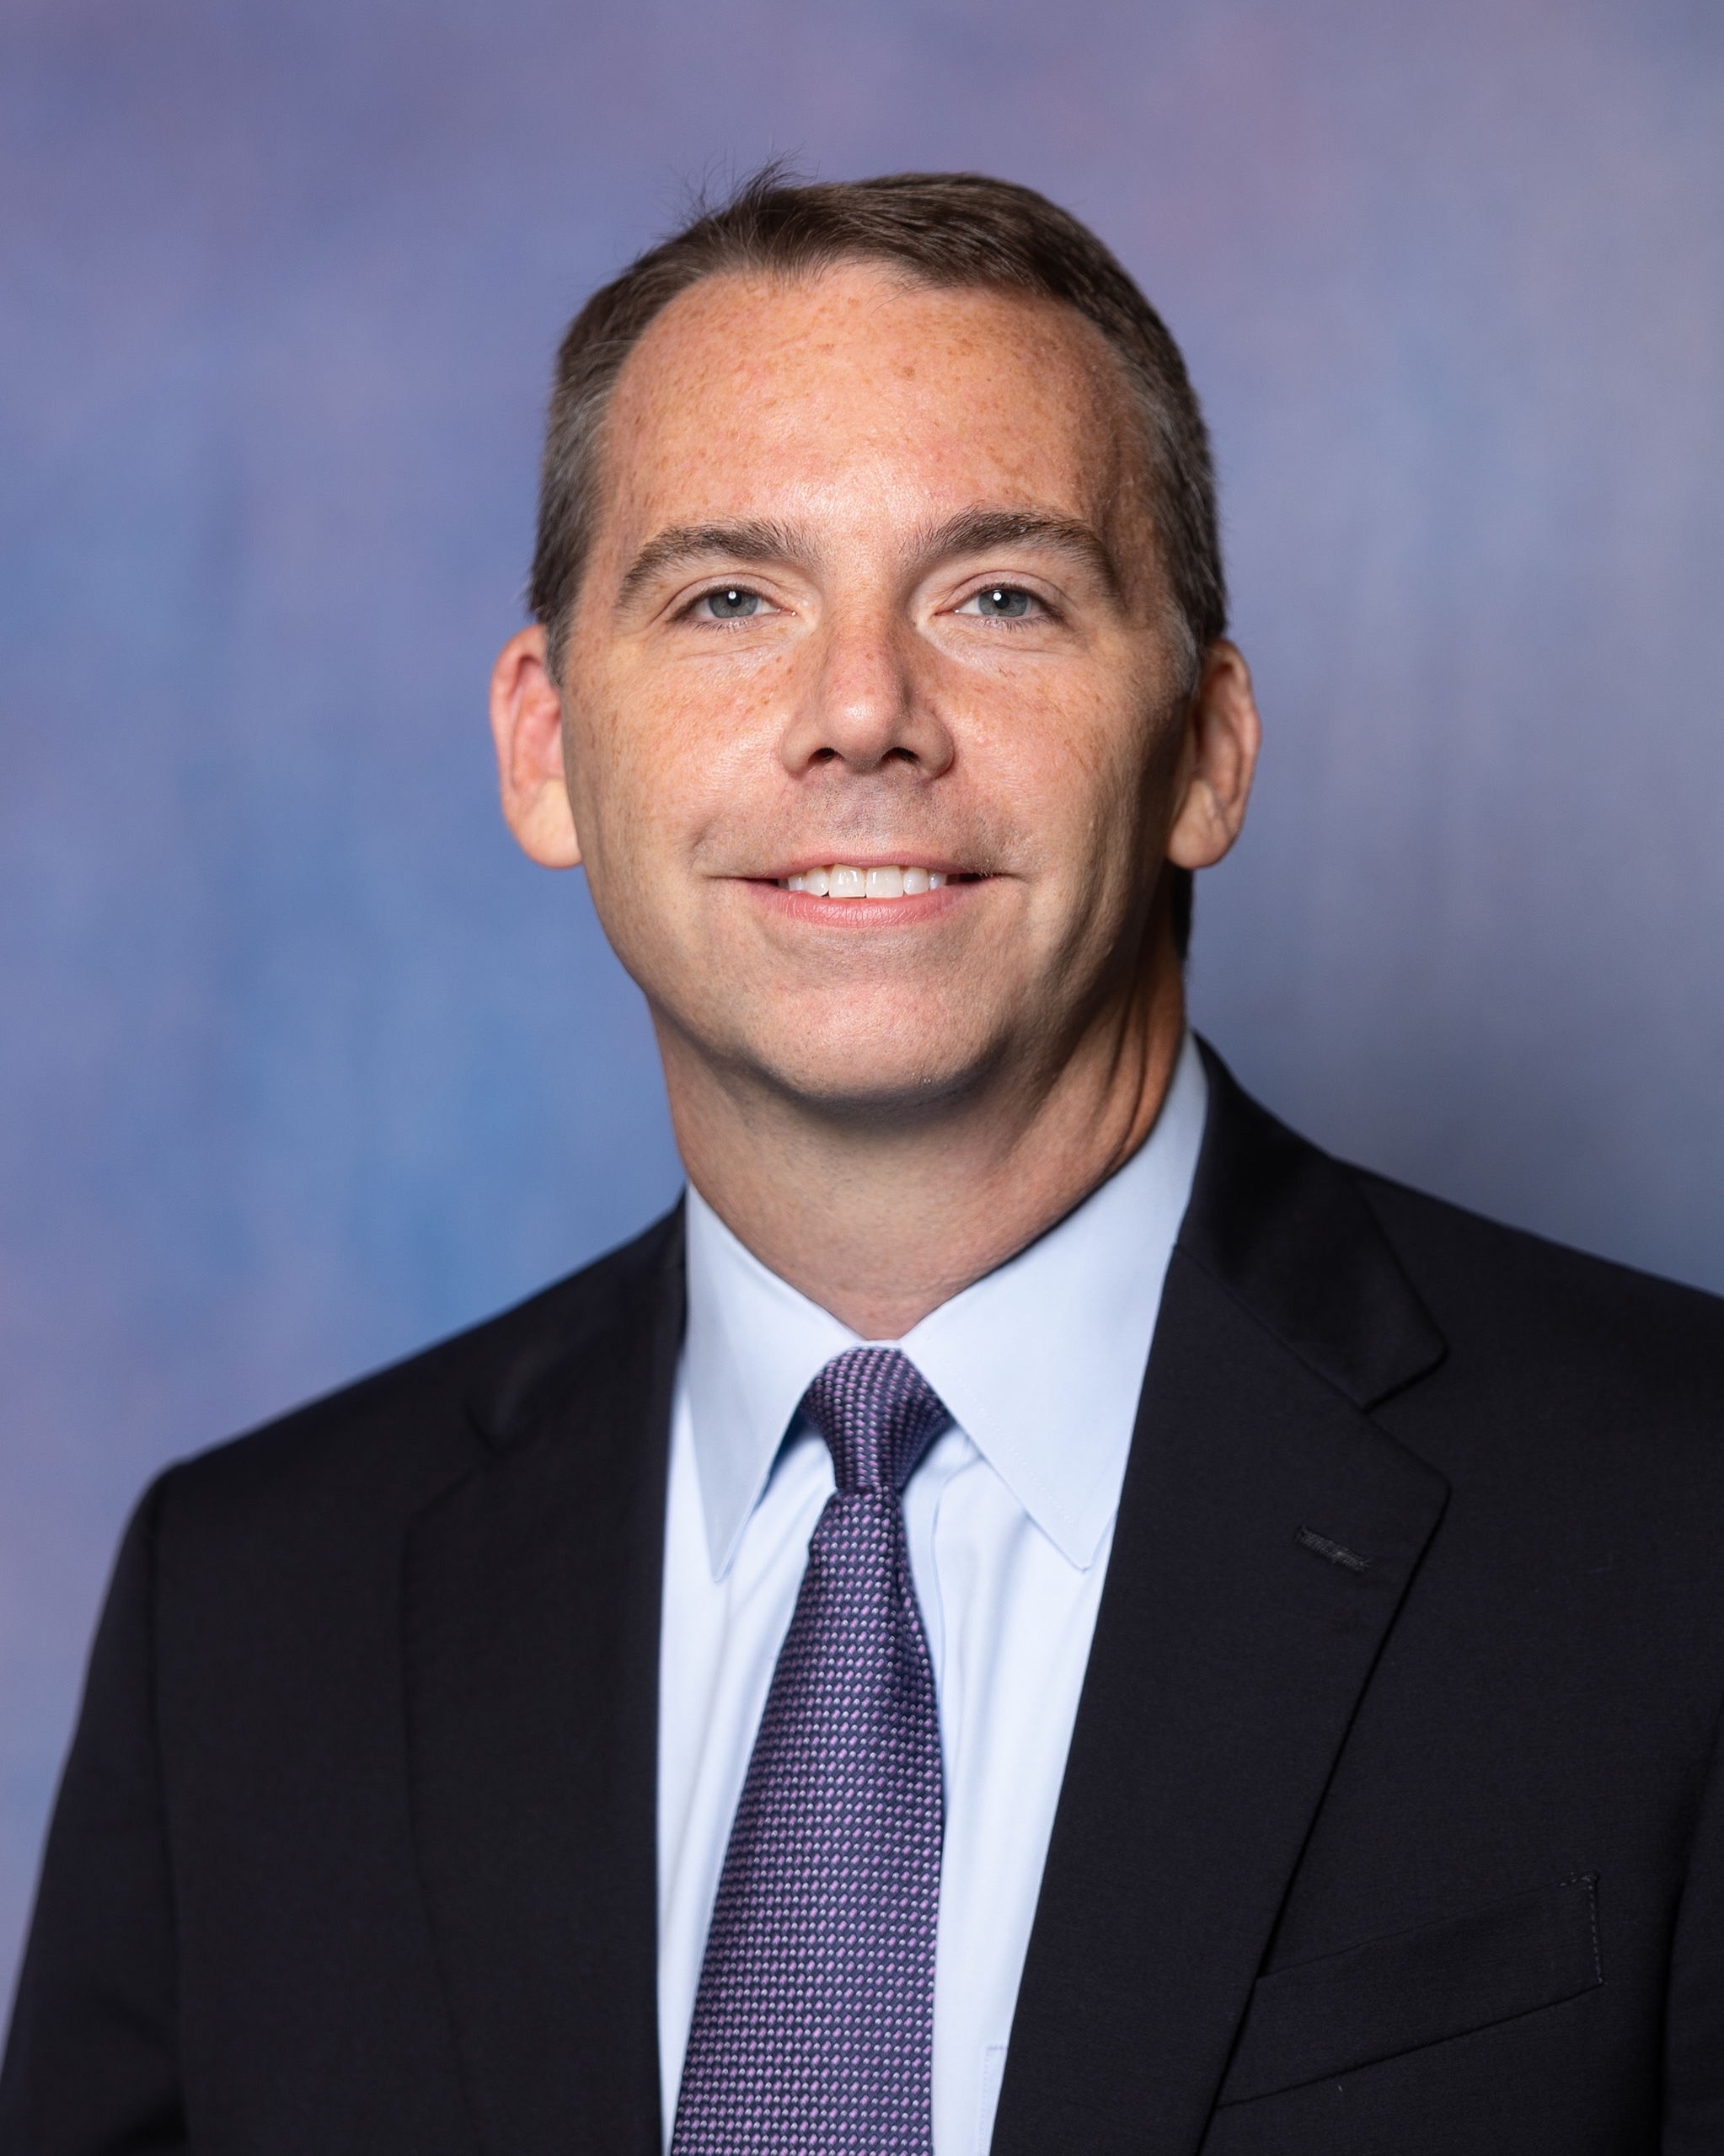
Dr. Chris Brune, Professor of Finance and George Young Chair of Business
Q: Saving for college feels overwhelming. Where does a family with young kids start?
A: College is expensive. And saving enough to make a meaningful difference can feel
overwhelming. If your children are young, the good news is that time is on your side.
It’s easy to underestimate the power of compounding over time. For example, $100 in
monthly savings for five years at an 8% rate of return would generate an ending balance
of about $7,350. If you change the time period to ten years, the ending balance grows
to $18,295. And if you change the time period to 15 years, the ending balance grows
to $34,600.
We tend to think about the impact of the savings amount and the rate of return on investment performance, but time is also important. Starting early — even if it’s with a small amount — allows you to accumulate more funds for college without breaking your budget every month.
QUICK DEFINITION: COMPOUND GROWTH
Money you invest earns returns, and then those returns earn returns of their own. So a dollar saved when your child is three has many more years to multiply than a dollar saved when they’re 16.
Q: With college a decade or more away, how should that money be invested?
A: With ten or fifteen years before your child starts school, you are generally in
a position to take more risk than if you’re staring at a freshman year that’s only
a few years away. That usually results in a larger allocation to stocks early on,
because there’s time to absorb the fluctuations in the market.
The good news is that some types of accounts — particularly 529 plans — may be structured to make some of these decisions for you. Just as your retirement plan may automatically lower the risk of your investments as you approach retirement, some plans can do the same with your college savings. That's another reason that it’s important to give some thought to the account type before you start making investment decisions.
QUICK DEFINITION: TARGET DATE FUND
A single investment that automatically becomes more conservative as a chosen date nears. It’s a common option inside 529 plans — pick the year college starts, and the fund handles the shift from growth-focused to safer investments for you.
Q: Should families invite grandparents to contribute?
A: Absolutely, invite them. If grandparents are willing and able, contributions to
a college savings plan are a great way for them to invest in their grandchildren's
future. Most state 529 plans make it simple to contribute directly online, for both
the owner and anyone else who would like to make a gift. Some grandparents even make
matching contributions on what a child earns from small jobs to stress the importance
of saving from an early age.
The way they give can matter, though, and this is a detail some families miss. Financial aid formulas weigh assets differently depending on who owns the account. Depending on the family, a 529 plan owned by a grandparent for the benefit of a grandchild may result in a more favorable financial aid calculation. It may be helpful to check with a financial aid office for specifics related to your situation, especially since guidelines sometimes change over time.
Think of it as an opportunity, not a transaction. A grandparent who gives toward a grandchild's education isn't just helping with a future bill. They're investing in the life of that grandchild in a way that will extend far beyond the four years that the child is in college. Many grandparents, if they're able to give, will see it that way.
QUICK DEFINITION: AVERAGE NET PRICE
Sticker price is what you often see reported. Net price is the average out-of-pocket costs after subtracting aid, like scholarships, grants and work study. This is significantly less than the sticker price for most families. You can find university’s net price on websites like Niche.com and every school is required to have a net price calculator on their website. Do the work to find out what you actually need to be saving for.
Q: If you could leave a young family with one thing, what would it be?
A: You just have to start. You don’t need a large sum to begin, and you don’t need
an advanced understanding of investments. Think through your objectives, select an
account type, choose an amount you can sustain, and be diligent in making contributions.
Read earlier posts in this series about choosing a college savings account and how to talk about priorities from the start.
How much should I save each month for college?
Enough to sustain the habit — the timeline matters as much as the amount. At an 8% rate of return, $100 a month grows to about $7,350 over five years, $18,295 over ten years and $34,600 over fifteen. Starting early, even with a small amount, lets you accumulate more without straining your budget each month.
How should I invest college savings while my child is young?
With ten or fifteen years before college, you're generally in a position to take more risk than a family a few years out — usually a larger allocation to stocks, since there's time to absorb market fluctuations. Some 529 plans handle this shift automatically, lowering risk as college approaches.
What is compound growth?
Money you invest earns returns, and those returns earn returns of their own. A dollar saved when your child is three has many more years to multiply than a dollar saved when they're sixteen.
Can grandparents contribute to a college savings account?
Yes, and most state 529 plans make it simple to contribute online. The way they give can matter — financial aid formulas weigh assets differently depending on who owns the account, and a grandparent-owned 529 may result in a more favorable calculation for some families. Check with a financial aid office for your situation, since guidelines change.
- Tags:
- College Planning
You Also Might Like
Recent